

Our Blog
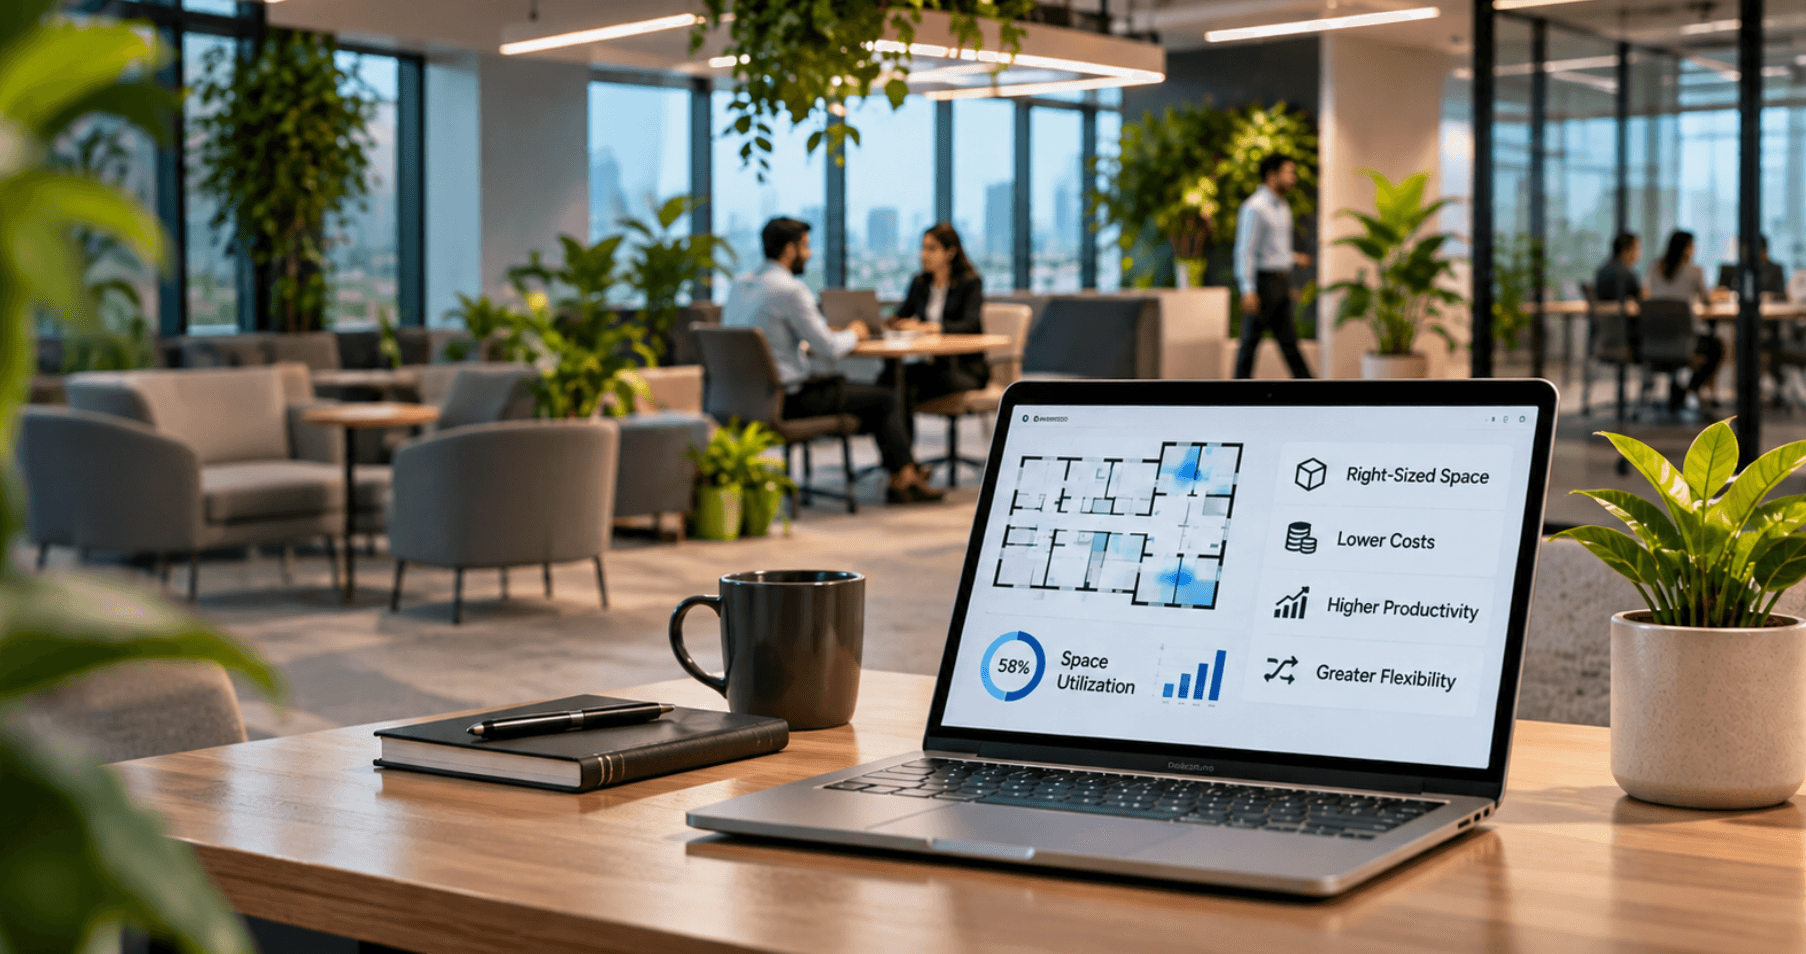
“We’re at 60% occupancy.” It sounds informative, but it barely is. A building at that level could be right-sized, badly oversized, or overflowing on the days that count. Occupancy is the figure everybody cites and the one that reveals the least.
To convince a finance team to reshape an office footprint in an Indian city, you can’t lean on a number that supports contradictory conclusions. You need a case built on stronger measures, and you should anticipate the pushback.
Even market-level figures depend on who is doing the counting. Crisil Ratings expects Grade A vacancy to ease to 15.5-16.0% by the end of the fiscal year, which sits alongside the 14.37% reported for Q3. The two cover different sets of buildings and use different definitions, which is precisely why no single figure should settle a lease decision.
The same applies within a company. The 2026 India survey found that 77% of occupiers report utilization above 50%. That is a healthy majority, yet an average conceals the distance between a crowded Wednesday and an empty Friday. A building that looks half-used on average can be completely full on its peak day. Demand sources vary too: BFSI took 24% of Q3 leasing and IT-BPM 22%. Sectors work differently, so a single sharing ratio across a whole portfolio is rarely correct.
There is a better measure. CFOs respond to cost per occupied seat, meaning total occupancy cost divided by the seats actually used on a peak day, far more than to cost per square foot. A building that looks economical per foot can be costly per person if few people use it.
Consider a hypothetical company with 1,000 employees and 1,000 desks at ₹1.2 lakh per desk per year, which comes to ₹12 crore. If attendance tops out around 750 on the busiest day, a sensible sharing ratio might remove 250 desks and save ₹3 crore annually, before fit-out and reconfiguration costs. The figures are invented for illustration, but the reasoning holds: the case rests on peak demand, not average attendance.
For a sense of what planners use, a Gurugram workplace-furniture vendor suggests that 0.6-0.7 desks per person is financially defensible even for cautious occupiers. That is a vendor’s view, so use it as a hypothesis to test against your own data.
Every leader asks this, and the research offers reassurance. A randomized trial involving 1,612 Trip.com employees found that hybrid working (three days in-office, two from home) had no negative impact on performance reviews, promotions or productivity. This offers valuable evidence that fewer office days don't necessarily mean lower performance. The authors of an MIT Sloan Management Review analysis state that no peer-reviewed research so far shows any advantage to a rigid five-day office model. That reflects an advocate’s reading of the literature, and the trial wasn’t conducted in India, so take it as one perspective.
India adds its own twist. A recent survey found that 77% of occupiers expect their India portfolios to grow over the next two years. For many firms the real challenge isn’t shrinking but expanding without adding space in step with headcount.
Flexible space has moved from a side option to the mainstream. Operators leased 191,306 seats across the top eight cities in the first half of 2026, up 68.4% year on year, with GCCs accounting for 44%. Crisil estimates that flex operators’ share of net absorption grew from about 14-15% in fiscal 2024 to roughly 20% in fiscal 2026, and it anticipates around 25% over the next two fiscals.
Meanwhile, Q3’s record 22.7 million sq ft of completions and the first vacancy increase in 12 quarters hand tenants more choice than they had a year ago. Rents are still climbing, so this market rewards preparation, not panic. Crisil adds a caveat: flex operators carry the risk of long landlord leases set against shorter tenant contracts, although renewal rates of 70-80% soften it. If you go the flex route, ask how stable your operator’s own commitments are. A smaller, better-located office can end up cheaper and more attractive than a large, tired one.
Start with at least 90 days of genuine usage data. Then examine peak demand by day and by team rather than company-wide averages, since one department’s busy Wednesday can vanish inside a quiet overall figure. Involve finance early too; if they help select the metrics, they are far likelier to trust the conclusions.
Pilot a target sharing ratio on a single floor before rolling it out. Price your options candidly: consolidate, lease elsewhere, renegotiate or relocate somewhere better. Record your assumptions so the plan can be revisited.
And count the soft costs. If peak days are crowded, meeting rooms are scarce and finding a desk takes ten minutes, people will work from home. A footprint that saves money but can’t cope with a busy Tuesday isn’t a saving.
A smarter footprint isn’t merely a smaller one. It is sized for peak demand, flexible in how it is leased and appealing enough that people choose to use it. Treat occupancy as a starting point, and bring cost per occupied seat to the finance table.
Mr. Aakash Jain
Director