

Our Blog
Quarterly Report: H1 2026 cumulative
Navigating market highs, rental bifurcation, and total cost of occupancy in a tightening market.
Hyderabad’s commercial office market maintained strong momentum in the first half of 2026, supported by sustained occupier demand, continued expansion by Global Capability Centres (GCCs), and growing activity across established office corridors.
Demand remained broad-based, led by multinational and technology-driven businesses, GCCs, IT and technology occupiers, BFSI, healthcare and pharmaceutical companies, along with increasing adoption of flexible office solutions. The market’s strengthening fundamentals reflect Hyderabad’s continued evolution as one of India’s leading commercial office destinations.
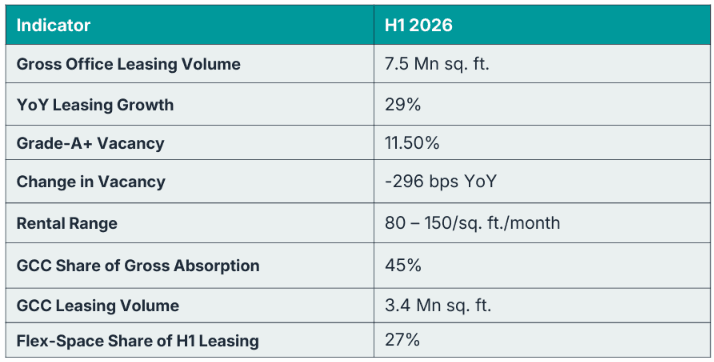
The market recorded strong leasing activity alongside improving vacancy levels and healthy rental growth, pointing towards sustained demand for quality commercial office space.
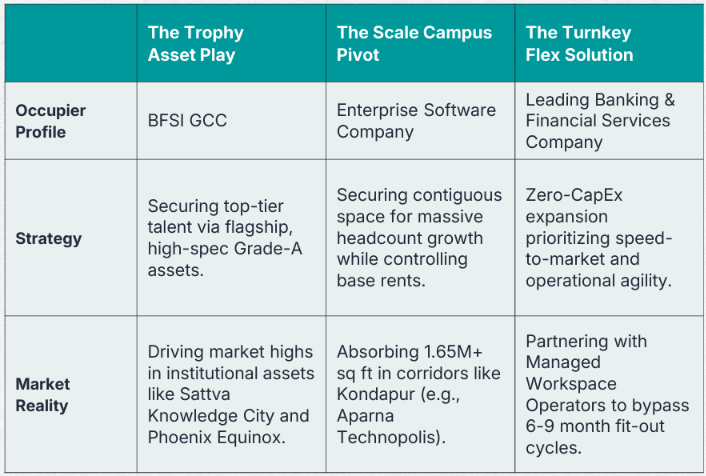
H1 2026 recorded exceptionally strong transactional activity, driven heavily by enterprise tech and global capability centers (GCCs).
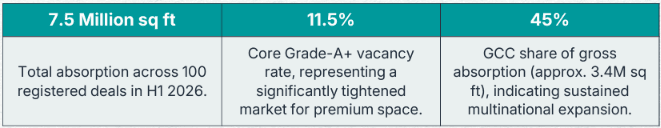
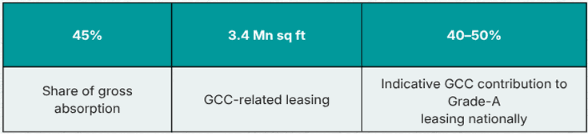
Global Capability Centres remain one of the strongest structural drivers of Hyderabad's office market. GCCs accounted for approximately 45% of gross office absorption during H1 2026, representing around 3.4 million sq ft of leasing activity. With 43 new GCCs recorded in H1 2026, the influx of international companies is reinforcing Hyderabad's position as a key destination for global operations. This is also expanding demand across IT, BFSI and other enterprise sectors.
Flexible workspace is becoming a significant component of Hyderabad's office demand, with flex operators accounting for 27% of H1 2026 leasing activity. The segment is gaining traction as occupiers seek greater flexibility, shorter commitment periods and scalable workplace solutions. Hyderabad also recorded 40,451 flex seats leased in H1 2026, up 170.8% YoY, highlighting the rapid expansion of flexible workspace adoption across the city.
Hyderabad's office market continued to show signs of tightening during H1 2026. Grade-A+ vacancy stood at 11.5%, representing a 296-basis-point improvement yearon-year. Average transacted office rents ranged from approximately ₹80–₹150per sq. ft. per month
Pricing is strictly bifurcated based on CapEx structure and asset maturity.
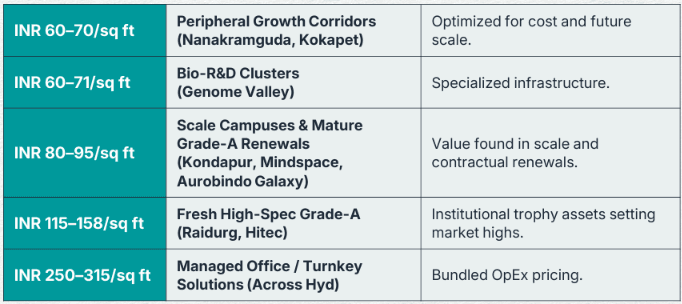
The Renewal Boon: Mature assets, signed at lower base rents with 12–15% annual escalation caps, are being renewed at market discounts.
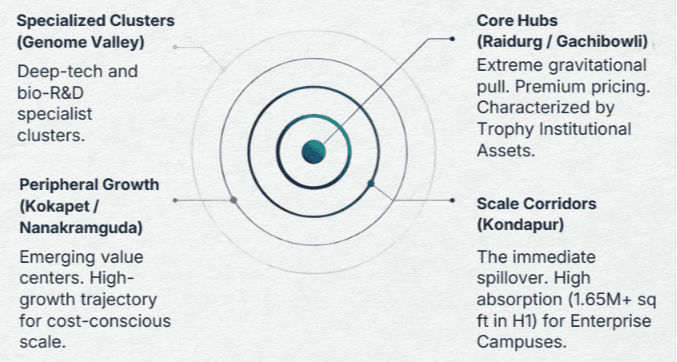
Gachibowli & Raidurg: Have emerged as the most active office corridor in Q2 2026, reflecting continued occupier preference for Hyderabad's western commercial belt.
Madhapur: Madhapur followed Gachibowli as another major leasing destination, supported by its established office ecosystem and strong connectivity.
Western Office Corridor, Nanakramguda: The western commercial belt continues to play a central role in Hyderabad's office market, supported by Grade-A developments, established businesses and expanding occupier demand.
IT & BPM: Technology-led businesses continue to represent a major component of office demand.
BFSI: Financial services companies remain an important source of conventional office leasing.
Healthcare & Pharma: Healthcare and pharmaceutical businesses continue to contribute to commercial office requirements.
Flexible Workspaces: Flex-space operators accounted for approximately 27% of H1 2026 leasing, highlighting the increasing importance offlexible workplace solutions.
GCC Expansion
Continued GCC activity is expected to remain a major source of Grade-A office demand.
Strong Enterprise Demand
Technology, BFSI, healthcare and pharmaceutical occupiers are expected to remain important demand contributors.
Flexible Workspace Growth
The growing share of flex-space leasing points towards continued demand for managed and flexible office solutions.
Western Corridor Strength
Gachibowli and Madhapur are expected to remain among Hyderabad's most important commercial office locations.
Healthy Supply Pipeline
With annual demand and new supply both expected to exceed 10 million sq ft, the market is entering another significant phase of expansion.
Hyderabad's commercial office market remains firmly on a growth trajectory. Strong H1 leasing, declining vacancy, rising rents and sustained GCC demand demonstrate the depth of occupier interest in the city. Gachibowli and Madhapur continue to anchor the commercial office landscape, while flexible workspace operators are gaining a larger role in meeting evolving occupier requirements. With annual office demand and new supply both expected to exceed 10 million sq ft in 2026, Hyderabad is positioned to remain one of India's key commercial office markets. For occupiers, investors and workspace providers, the market presents a combination of strong demand, expanding supply and evolving workplace requirements, creating opportunities across both traditional and flexible office formats.
Mr. Aakash Jain
Director